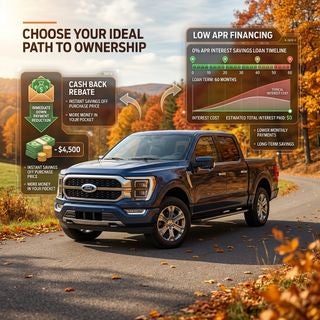
Cash back rebates immediately subtract money from the purchase price of a vehicle, whereas low APR financing lowers the interest percentage charged on your loan balance over time. A cash rebate provides instant equity upfront, while promotional low-interest financing delivers continuous savings throughout the loan term. Determining which incentive yields greater value depends entirely on the total amount financed, the length of the loan repayment term, and the alternative market interest rate you qualify for through standard lending channels.
When manufacturers release promotional incentives, buyers are typically faced with an either-or scenario rather than the ability to stack both offers. A customer cash offer acts as direct down payment assistance or a price reduction, which shrinks the principal loan balance from day one. In contrast, financing offers through Ford Credit—such as current promotional APR for 36 months or promotional APR for 72 months—keep the principal balance higher while eliminating or heavily discounting interest charges. On larger purchases like a full-size truck or a three-row SUV, avoiding interest over five or six years often generates thousands of dollars in cumulative savings, easily outpacing a modest upfront rebate.
Evaluating these offers requires looking beyond the monthly payment figure to compare the total lifecycle cost of the loan. Families comparing options on our sales lot usually want to see how a cash incentive balances against a reduced interest rate over a five-year term before making a final commitment. If you are planning a trip to discuss current incentive structures with our finance team, you can drop by our showroom on Pennsylvania Avenue or give our staff a quick call to walk through real-time rate comparisons on specific models.
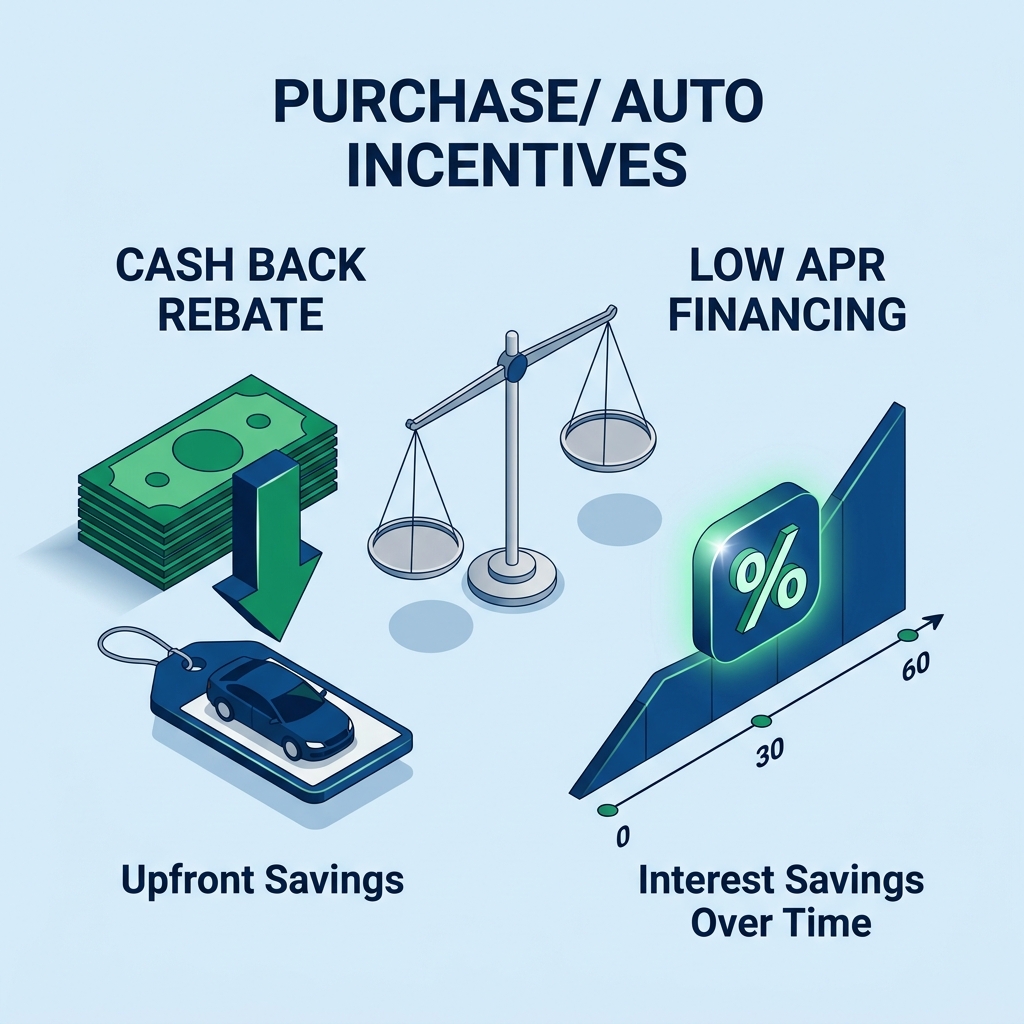
Table of Contents
- How Do Loan Amount, Down Payment Size, and Math Determine Your Savings?
- Is current promotional APR Available on 72-Month Auto Loans and What Credit Score Is Required?
- How Soon Can You Refinance After Taking a Cash Rebate?
- What Free Online Tools and Sales Tax Rules Impact Your Financing Choice?
- Common Questions About Low APR Rates Versus Cash Rebates
- Explore New Vehicle Financing Options at Tri State Ford
How Do Loan Amount, Down Payment Size, and Math Determine Your Savings?
Mathematical total-cost calculations favor low APR financing when borrowing large sums over long terms, whereas large cash down payments make upfront customer rebates more financially advantageous. The total principal financed dictates how much interest accrues over time. Because interest accrues as a percentage of the remaining principal each month, higher starting balances paired with standard market interest rates rapidly generate significant interest charges, allowing a low promotional interest rate to outperform an upfront cash discount.
Consider how these calculations apply to a high-capability vehicle like the 2026 Ford F-150. On an F-150 King Ranch 4x4 SuperCrew 5-1/2’ Box featuring a 3.5L V6 engine, a SelectShift® transmission, and an EPA rating of 17 city / 23 hwy, the base MSRP is $69,625 with a $2,795 destination charge. Financing a balance of that size over 60 or 72 months at standard commercial auto loan rates can accumulate major interest overhead. Accepting a low promotional interest rate wipes out the bulk of those interest fees, producing overall lifetime savings that easily dwarf a standardized cash back offer.
Conversely, down payment size dramatically alters this balance. If a buyer puts down a substantial cash down payment or carries significant vehicle trade-in equity, the net loan amount drops. When borrowing a smaller sum—such as on an entry-level F-150 STX SuperCab 6-1/2’ Box with a base MSRP of $44,855—a standard $1,500 or $2,500 cash rebate eliminates a higher percentage of the total vehicle price. For suburban commuters around Calcutta taking shorter 36-month or 48-month loan terms, reducing the initial principal balance with a rebate yields lower net payments than taking a minor rate reduction on an already small loan balance.
To run these numbers accurately, you must multiply the monthly payment under both scenarios by the total number of loan months, then add any upfront fees to see the total out-of-pocket cost. Buyers exploring our pre-owned single-owner vehicle inventory often utilize similar total-cost math when weighing standard bank auto loans against lower cash sale prices.
Pricing
Pricing by trim
| Feature | King Ranch 4x4 SuperCrew 5-1/2’ Box | King Ranch 4x4 SuperCrew 6-1/2’ Box | King Ranch SuperCrew 5-1/2’ Box | Lariat 4x4 SuperCrew 5-1/2’ Box | Lariat 4x4 SuperCrew 6-1/2’ Box | Lariat SuperCrew 5-1/2’ Box | Platinum 4x4 SuperCrew 5-1/2’ Box | Platinum 4x4 SuperCrew 6-1/2’ Box | Platinum SuperCrew 5-1/2’ Box | Police Responder 4x4 SuperCrew 5-1/2’ Box | Raptor 4x4 SuperCrew 5-1/2’ Box | STX 4x4 SuperCab 6-1/2’ Box | STX 4x4 SuperCrew 5-1/2’ Box | STX SuperCab 6-1/2’ Box | STX SuperCrew 5-1/2’ Box | Tremor 4x4 SuperCrew 5-1/2’ Box | XL 4x4 Regular Cab 6-1/2’ Box | XL 4x4 Regular Cab 8’ Box | XL 4x4 SuperCab 6-1/2’ Box | XL 4x4 SuperCrew 5-1/2’ Box | XL 4x4 SuperCrew 6-1/2’ Box | XL Regular Cab 6-1/2’ Box | XL Regular Cab 8’ Box | XL SuperCab 6-1/2’ Box | XL SuperCrew 5-1/2’ Box | XLT 4x4 SuperCab 6-1/2’ Box | XLT 4x4 SuperCrew 5-1/2’ Box | XLT 4x4 SuperCrew 6-1/2’ Box | XLT SuperCab 6-1/2’ Box | XLT SuperCrew 5-1/2’ Box |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- |
| Base MSRP | $69,625 | $69,930 | $65,825 | $63,360 | $63,965 | $59,560 | $72,600 | $72,905 | $68,800 | $52,350 | $79,005 | $48,655 | $51,070 | $44,855 | $47,190 | $64,915 | $44,600 | $42,305 | $45,400 | $47,820 | $50,475 | $39,585 | $37,290 | $41,600 | $43,935 | $49,495 | $51,915 | $54,555 | $45,695 | $48,055 |
| Destination charge | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,595 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 | $2,795 |
Dimensions & Capacity
Capacity and dimensions by trim
| Feature | King Ranch 4x4 SuperCrew 5-1/2’ Box | King Ranch 4x4 SuperCrew 6-1/2’ Box | King Ranch SuperCrew 5-1/2’ Box | Lariat 4x4 SuperCrew 5-1/2’ Box | Lariat 4x4 SuperCrew 6-1/2’ Box | Lariat SuperCrew 5-1/2’ Box | Platinum 4x4 SuperCrew 5-1/2’ Box | Platinum 4x4 SuperCrew 6-1/2’ Box | Platinum SuperCrew 5-1/2’ Box | Police Responder 4x4 SuperCrw 5-1/2’ Box | Raptor 4x4 SuperCrew 5-1/2’ Box | STX 4x4 SuperCab 6-1/2’ Box | STX 4x4 SuperCrew 5-1/2’ Box | STX SuperCab 6-1/2’ Box | STX SuperCrew 5-1/2’ Box | Tremor 4x4 SuperCrew 5-1/2’ Box | XL 4x4 Regular Cab 6-1/2’ Box | XL 4x4 Regular Cab 8’ Box | XL 4x4 SuperCab 6-1/2’ Box | XL 4x4 SuperCrew 5-1/2’ Box | XL 4x4 SuperCrew 6-1/2’ Box | XL Regular Cab 6-1/2’ Box | XL Regular Cab 8’ Box | XL SuperCab 6-1/2’ Box | XL SuperCrew 5-1/2’ Box | XLT 4x4 SuperCab 6-1/2’ Box | XLT 4x4 SuperCrew 5-1/2’ Box | XLT 4x4 SuperCrew 6-1/2’ Box | XLT SuperCab 6-1/2’ Box | XLT SuperCrew 5-1/2’ Box |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- | :-- |
| Seating | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 5 | 3 | 3 | 6 | 6 | 6 | 3 | 3 | 6 | 6 | 6 | 6 | 6 | 6 | 6 |
| Cargo | 52.8 cu ft | 62.3 cu ft | 52.8 cu ft | 52.8 cu ft | 62.3 cu ft | 52.8 cu ft | 52.8 cu ft | 62.3 cu ft | 52.8 cu ft | 52.8 cu ft | 52.8 cu ft | 62.3 cu ft | 52.8 cu ft | 62.3 cu ft | 52.8 cu ft | — | 62.3 cu ft | 77.4 cu ft | 62.3 cu ft | 52.8 cu ft | 62.3 cu ft | 62.3 cu ft | 77.4 cu ft | 62.3 cu ft | 52.8 cu ft | 62.3 cu ft | 52.8 cu ft | 62.3 cu ft | 62.3 cu ft | 52.8 cu ft |
| Curb weight | 5,096 lbs | 5,143 lbs | 5,096 lbs | 5,020 lbs | 5,122 lbs | 5,020 lbs | 5,096 lbs | 5,143 lbs | 5,096 lbs | 5,020 lbs | 5,710 lbs | 4,895 lbs | 4,941 lbs | 4,641 lbs | 4,687 lbs | 5,267 lbs | 4,655 lbs | 4,679 lbs | 4,895 lbs | 4,941 lbs | 5,122 lbs | 4,391 lbs | 4,396 lbs | 4,641 lbs | 4,687 lbs | 4,895 lbs | 4,941 lbs | 5,122 lbs | 4,641 lbs | 4,687 lbs |
| Towing | 10,400 lbs | 10,800 lbs | 10,400 lbs | 9,300 lbs | 9,200 lbs | 9,300 lbs | 10,400 lbs | 10,800 lbs | 10,400 lbs | — | 8,200 lbs | 7,400 lbs | 7,500 lbs | 7,500 lbs | 7,600 lbs | 9,300 lbs | 9,400 lbs | 7,500 lbs | 7,400 lbs | 7,500 lbs | 9,200 lbs | 9,000 lbs | 7,400 lbs | 7,500 lbs | 7,600 lbs | 7,400 lbs | 7,500 lbs | 9,200 lbs | 7,500 lbs | 7,600 lbs |
| Payload | 1,945 lbs | 2,000 lbs | 1,945 lbs | 2,020 lbs | 2,020 lbs | 2,020 lbs | 1,945 lbs | 2,000 lbs | 1,945 lbs | 2,030 lbs | 1,410 lbs | 1,600 lbs | 1,650 lbs | 1,670 lbs | 1,685 lbs | 1,725 lbs | 1,740 lbs | 1,715 lbs | 1,600 lbs | 1,650 lbs | 2,020 lbs | 1,810 lbs | 1,775 lbs | 1,670 lbs | 1,685 lbs | 1,600 lbs | 1,650 lbs | 2,020 lbs | 1,670 lbs | 1,685 lbs |
Is current promotional APR Available on 72-Month Auto Loans and What Credit Score Is Required?
Promotional current promotional APR financing for 72-month terms is occasionally offered during major manufacturer sales events, but eligibility is restricted strictly to high-tier credit applicants and specific vehicle trims. Lenders extend these zero-interest long-term loans selectively because carrying a loan balance for six years without earning interest exposes the financial institution to inflation and default risks. Consequently, manufacturers restrict these top-tier rates to buyers demonstrating exceptional credit history and financial stability.
Qualifying for zero percent interest or the lowest tier of promotional APR usually requires a credit score of 740 or higher, often categorized as Tier 1 or Tier 1+ credit by captive lenders like Ford Credit. Beyond the credit score threshold, underwriters evaluate your debt-to-income ratio, length of employment, and past vehicle payment history. Borrowers with credit scores in the mid-600s may still qualify for reduced promotional rates—such as promotional APR or 3.9% APR—even if the zero-percent banner offer is reserved for higher tiers.
If your credit score falls just below the tier-one cutoff, submitting a credit application with a qualified co-signer or placing a larger cash down payment can sometimes elevate your approval tier. Buyers searching for high value outside of new vehicle incentives frequently browse our certified pre-owned Ford lineup, where factory-backed warranty protection pairs with competitive credit union or institutional lending options. Completing a secure online credit application allows our finance specialists to determine your exact rate tier before you shop.
How Soon Can You Refinance After Taking a Cash Rebate?
You can refinance an auto loan almost immediately after taking advantage of a manufacturer cash back rebate, provided your loan agreement does not include a specific prepayment penalty clause. Most standard vehicle contracts executed today are simple-interest loans without early payoff fees. This structure allows savvy buyers to accept an upfront customer cash rebate paired with standard dealer financing, then quickly refinance the remaining loan balance with a third-party lender or credit union to secure a lower market interest rate.
While no legal restriction prevents refinancing right away, practical administrative timelines usually mandate a brief waiting period of 60 to 90 days. This window is necessary for several administrative steps to clear:
- The state bureau of motor vehicles must process the original title registration and record the initial lienholder.
- The original lending institution must establish your active account and generate a formal loan account number.
- The refinancing credit union or bank requires an official payoff quote and clear title documentation from the primary lender before issuing funds.
Refinancing too quickly—before the initial account is fully registered—can cause administrative delays or duplicate title filing fees. Additionally, buyers who trade in a vehicle must wait for the old balance to settle. If you plan to leverage trade equity toward your purchase before considering a future refinance, you can obtain a Kelley Blue Book instant cash offer online or utilize our trade-in valuation tool to establish your accurate vehicle equity upfront.
What Free Online Tools and Sales Tax Rules Impact Your Financing Choice?
Free online auto payment calculators let you model side-by-side total costs by entering purchase prices, trade-in values, loan terms, and interest rates. Captive manufacturer websites, financial comparison portals, and dealership credit tools allow buyers to adjust down payment inputs dynamically. These digital tools highlight the exact point where a cash rebate yields greater savings than a discounted interest rate, helping shoppers remove guesswork before visiting a showroom.
State sales tax regulations represent another vital variable in the mathematical equation. In many states, manufacturer cash rebates are deducted from the selling price before state and local sales tax is calculated. For instance, if a buyer accepts a $3,000 cash rebate on a $40,000 SUV, the taxable sale price drops to $37,000, immediately saving the buyer additional money in reduced sales tax obligations. However, in states where tax is assessed on the full vehicle price prior to rebate application, that secondary tax benefit disappears.
Local commuting habits and vehicle usage also influence how quickly you pay off a vehicle. For drivers working near Boardman who travel daily along major suburban retail corridors, high annual mileage can cause faster vehicle depreciation. In high-mileage scenarios, taking a cash rebate upfront builds immediate vehicle equity, helping protect against negative equity if you decide to trade the vehicle in after three or four years rather than holding the loan for its full six-year term.
Common Questions About Low APR Rates Versus Cash Rebates
Q: Do credit unions offer special loan discounts for new vehicle purchases? Many local credit unions offer interest rate discounts ranging from 0.25% to 0.50% for setting up automatic electronic loan payments or purchasing energy-efficient vehicles. When paired with a manufacturer cash rebate, securing an aggressive low rate from a credit union can sometimes deliver lower total loan costs than taking the manufacturer's promotional financing offer alone.
Q: How does a down payment change the math on low APR versus cash back? A larger down payment reduces the principal loan balance, which directly reduces the total interest that can accrue over the life of the loan. As the total amount financed gets smaller, the monetary value of a low interest rate decreases, making an upfront cash rebate significantly more valuable to the buyer.
Q: Can I combine a promotional low APR rate with a manufacturer cash rebate on the same vehicle? In most cases, retail incentives are structured as standalone choices where buyers must choose either the low interest rate or the customer cash rebate. However, manufacturers occasionally offer specialized bonus cash or regional down payment assistance that can be stacked with promotional low-APR financing on select trims and model years.
Q: Does taking a cash rebate lower the vehicle sales tax I owe? In jurisdictions where state regulations allow rebates to be subtracted prior to tax calculation, taking a cash rebate lowers the net purchase price subject to sales tax. You should verify local state tax guidelines with your finance manager during the purchasing process to calculate exact out-of-pocket tax obligations.
Q: What credit documentation do I need to bring to get pre-approved for promotional rates? To qualify for promotional financing rates smoothly, buyers should bring recent pay stubs or proof of income, a valid driver's license, current proof of auto insurance, and documentation for any trade-in vehicle title or existing payoff statement. Bringing these items accelerates loan underwriting approval.
Explore New Vehicle Financing Options at Tri State Ford
Selecting the ideal combination of manufacturer incentives, trade-in equity, and loan structures requires clear side-by-side comparisons tailored to your household budget. Our financing staff specializes in laying out transparent comparisons between low-APR promotional rates and customer cash rebates, ensuring you make an informed financial choice on your next vehicle purchase.
Whether you are looking for a heavy-duty work truck, a fuel-efficient commuter, or a spacious family SUV, our sales team is ready to walk you through current incentives and trim options. We invite you to explore our new Ford vehicle inventory online to see current model availability and incentive structures. When you are ready for a test drive or a personalized payment calculation, call our sales department at (330) 462-7578 or drop by our dealership showroom to get started.
Keep Your Vehicle Running Strong
Keep your vehicle performing at its best with our service team:
© 2026 Tri State Ford. All rights reserved.