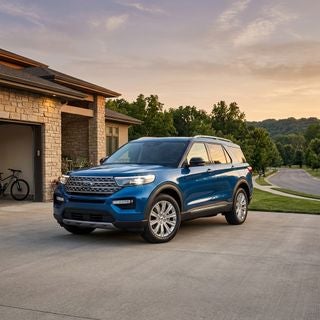
A vehicle lease functions as a long-term agreement where you pay for the projected depreciation of a new vehicle over a set timeframe—typically 24 to 36 months—rather than financing its total purchase price. You pay an initial amount at signing, follow a structured monthly payment schedule, adhere to agreed-upon annual mileage caps, and return or buy the vehicle when the contract ends.
Leasing provides a straightforward way to drive a new vehicle with different monthly payments than traditional buying. Because payments are based on expected vehicle depreciation rather than the full purchase value, drivers enjoy reduced monthly costs along with coverage under the 3-year/36,000-mile bumper-to-bumper warranty and 5-year/60,000-mile powertrain warranty.
When you enter a lease contract, you agree on key parameters upfront:
- The contract length (most commonly 24, 36, or 39 months)
- The annual mileage allowance (typically 10,000, 12,000, or 15,000 miles per year)
- The scheduled monthly payment information and due date
- End-of-term options, including returning the vehicle, starting a new lease, or purchasing the car outright
Driving along the riverfront bluffs and hilly terrain of East Liverpool means having a durable, modern vehicle matters for daily commuting. Leasing allows drivers to transition into an updated vehicle every few years without worrying about long-term mechanical wear or resale depreciation. To explore current lease terms or tour our showroom at 1503 Pennsylvania Ave, East Liverpool, OH 43920, drop by our dealership location or call our finance team at (330) 462-7578.
Table of Contents
- What Is the Main Difference Between Leasing and Buying a Vehicle?
- Who Benefits Most From Leasing a Ford Model?
- How Are Lease Payments Calculated: Capitalized Cost, Residual Value, and Money Factor
- Should You Make a Down Payment and What Credit Score Is Needed to Lease?
- How Do Mileage Limits, Lease Swaps, and End-of-Lease Buyouts Work?
- Common Questions About Leasing a Ford Vehicle
- Exploring Your Ford Leasing Options at Tri State Ford
What Is the Main Difference Between Leasing and Buying a Vehicle?
The main distinction between leasing and buying comes down to financial equity and vehicle ownership structure. Buying finances the full purchase price of a vehicle until you pay off the loan and own the title, whereas leasing finances only the vehicle's estimated value loss during the time you drive it.
When choosing between these purchase paths, several core operational factors stand out:
- Monthly Payment Structure: Leasing generally yields monthly payments compared to financing the total price of a new vehicle because you pay only for depreciation plus a rent charge.
- Ownership Equity: Buying builds long-term vehicle equity as payments accrue toward total ownership. Leasing operates like a long-term vehicle setup where you return the keys at contract end without trade-in equity, unless market conditions create positive equity above the preset buyout price.
- Vehicle Customization: Purchased vehicles can be modified, repainted, or fitted with custom aftermarket accessories without restriction. Leased vehicles must be maintained in factory condition and returned without permanent alterations.
- Warranty and Maintenance: Leased models stay continuously protected under original manufacturer warranties throughout the typical 36-month lease cycle, protecting drivers from out-of-pocket costs on major mechanical repairs.
Whether you prefer long-term ownership or regular updates to vehicle tech, reviewing vehicle choices helps clarify your decision. You can explore our inventory of brand-new Ford models, view current manufacturer lease offers, or check out our selection of single-owner pre-owned vehicles to compare purchase choices side by side.
Pricing
Pricing by trim
| Feature | Active AWD | Active FWD | Platinum AWD | ST-Line AWD |
|---|---|---|---|---|
| Base MSRP | $31,750 | $30,350 | $37,940 | $32,595 |
| Destination charge | $1,495 | $1,495 | $1,495 | $1,495 |
Pricing (continued)
| Feature | ST-Line Elite AWD 2.0L | ST-Line FWD | ST-Line Select AWD 2.0L |
|---|---|---|---|
| Base MSRP | $38,935 | $31,195 | $35,015 |
| Destination charge | $1,495 | $1,495 | $1,495 |
Who Benefits Most From Leasing a Ford Model?
Leasing offers the greatest value to drivers who prefer upgrading to updated tech every two to three years, maintain predictable driving habits, and prefer keeping monthly expenses low under full factory warranty protection.
A vehicle lease is well-suited for several types of drivers:
- Tech-Oriented Drivers: Commuters who want the latest cabin features, including SYNC 4A and Ford Co-Pilot360 driver-assist technologies, can refresh their vehicle technology every few years.
- Predictable-Distance Commuters: Drivers taking daily trips along State Route 170 in Calcutta usually find that standard 12,000-mile or 15,000-mile annual caps fit their daily driving patterns cleanly without triggering excess mileage fees.
- Budget-Conscious Families: Families needing generous passenger room and safety tech benefit from lower monthly payments on full-size or midsize SUVs without committing to a 72-month purchase loan.
For example, a driver leasing a 2026 Ford Escape with its 1.5L engine paired with an automatic 8-speed transmission gets an EPA-estimated 26 city / 32 hwy MPG alongside about 37.5 cu ft of rear cargo space. This delivers modern capability and space for weekend activities without long-term commitment. To keep your current vehicle running at peak performance, you can select factory-approved replacement tires, or if you prefer long-term ownership with low mileage, browse our certified pre-owned Ford inventory.
How Are Lease Payments Calculated: Capitalized Cost, Residual Value, and Money Factor
Lease payments are calculated by determining net capitalized cost, subtracting the vehicle's estimated residual value at term end, and adding a finance fee known as the money factor across the contract months.
Understanding the underlying math behind your lease agreement helps clarify how monthly payments are structured:
- Gross Capitalized Cost: The agreed-upon sale price of the vehicle, including any selected option packages or mandatory dealer processing fees.
- Net Capitalized Cost: The gross capitalized cost minus any capitalized cost reductions, such as cash down payments, manufacturer incentives, or trade-in equity.
- Residual Value: The leasing company’s predetermined projection of what the vehicle will be worth when the lease contract ends. Higher residual values lead to lower monthly payments because the vehicle depreciates less over the lease term.
- Money Factor: The lease charge expressed as a small decimal fraction (for example, 0.0025). Multiplying the money factor by 2,400 yields the equivalent Annual Percentage Rate (APR).
To see how MSRP affects lease pricing, consider the trim breakdown of the 2026 Ford Escape lineup. The baseline Active FWD carries a Base MSRP of $30,350, while adding all-wheel drive moves the Active AWD to $31,750. Sportier styling on the ST-Line FWD starts at $31,195, and the ST-Line AWD sits at $32,595. Upgrading to the punchier 2.0L engine with SelectShift® in the ST-Line Select AWD 2.0L brings the Base MSRP to $35,015. The luxury-oriented Platinum AWD starts at $37,940, while the top-tier ST-Line Elite AWD 2.0L reaches $38,935. Each model carries a mandatory $1,495 destination charge. Higher trims carry higher initial capitalized costs, but strong residual values keep monthly lease payments competitive.
Drivers looking to lower their net capitalized cost can start by estimating your trade-in value online to see how current vehicle equity can reduce overall monthly lease costs.
Should You Make a Down Payment and What Credit Score Is Needed to Lease?
Placing a large down payment on a leased vehicle is generally discouraged because upfront capital reduction payments are non-refundable if the vehicle is totaled or stolen early in the lease, while securing top-tier lease rates typically requires a credit score of 720 or higher.
When structuring a lease, understanding upfront money and credit requirements protects your wallet:
- The Down Payment Risk: On a financed purchase, a down payment builds equity immediately. On a lease, a down payment—referred to as a capitalized cost reduction—simply prepays a portion of the depreciation. If the vehicle is involved in a severe collision or stolen during the first few months, gap protection covers the difference between market value and lease balance, but any cash paid upfront at signing is lost.
- Credit Tier Qualifications: Leasing companies structure interest rates (money factors) into distinct credit tiers. A credit score above 720 typically qualifies applicants for Tier 1 rates, securing the lowest possible money factor. Scores between 660 and 719 usually qualify for competitive lease terms, though slightly higher money factors may apply.
- Optimal Upfront Strategy: Paying minimum drive-off fees—covering the first month's payment, registration, and mandatory acquisition fees—is often the safest approach. This keeps your cash liquid while maintaining a predictable monthly payment.
Shoppers comparing lease options on our showroom floor often ask whether placing thousands down upfront saves money long-term, and our finance team explains that preserving cash while rolling incentives into net capitalized cost offers better financial protection. You can verify your current leasing tier by submitting an online credit application with our finance desk.
How Do Mileage Limits, Lease Swaps, and End-of-Lease Buyouts Work?
Lease agreements establish strict annual mileage limits with per-mile charges for overages, allow contract assumption through formal lease swaps, and provide a fixed-price buyout option at term completion.
Managing operational parameters during and after your lease contract ensures a smooth experience:
- Mileage Allowance Structures: Standard lease contracts offer annual mileage tiers of 10,000, 12,000, or 15,000 miles. Exceeding your cumulative contract limit results in excess mileage charges at vehicle turn-in, typically ranging between $0.15 and $0.25 per excess mile. Purchasing extra miles upfront during initial lease structuring is significantly less expensive than paying per-mile penalties at return.
- Lease Transfers and Swaps: If your driving needs change mid-contract, a formal lease swap allows another qualified individual to take over your remaining lease term and monthly payments through lender approval.
- End-of-Lease Buyout Option: Every lease contract specifies a fixed purchase option price equal to the vehicle's residual value. If market prices make the car worth more than the preset residual figure, executing a lease buyout lets you purchase the vehicle outright without paying wear-and-tear or excess mileage charges.
For business owners needing high-mileage utility, structured vehicle options extend beyond consumer SUVs. You can evaluate our commercial F-Series work truck inventory to evaluate specialized commercial purchasing and financing arrangements tailored for heavy-duty operational demands.
Fuel Economy
Fuel economy and range by trim
| Feature | Active AWD | Active FWD | Platinum AWD | ST-Line AWD |
|---|---|---|---|---|
| MPG | 26 city / 32 hwy / 28 combined | 27 city / 34 hwy / 30 combined | 23 city / 31 hwy / 26 combined | 26 city / 32 hwy / 28 combined |
Fuel Economy (continued)
| Feature | ST-Line Elite AWD 2.0L | ST-Line FWD | ST-Line Select AWD 2.0L |
|---|---|---|---|
| MPG | 23 city / 31 hwy / 26 combined | 27 city / 34 hwy / 30 combined | 23 city / 31 hwy / 26 combined |
Common Questions About Leasing a Ford Vehicle
Q: What happens if I exceed my lease mileage allowance before the contract ends?
Exceeding your total cumulative mileage limit results in excess mileage fees when you return the vehicle, calculated at the per-mile rate stated in your contract (typically between $0.15 and $0.25 per mile). However, if you choose to execute an end-of-lease buyout or trade the vehicle in toward a new purchase where market value covers the balance, excess mileage charges do not apply.
Q: Can I end my car lease early or turn in the vehicle before contract expiration?
Early lease termination is permitted by most lenders, but it usually involves paying the difference between the remaining contract balance and the vehicle’s current wholesale value, along with an early termination fee. Alternative options include transferring the lease to a qualified buyer through a formal lease swap or trading the vehicle in early if market equity supports a buyout.
Q: Is routine vehicle maintenance included in a standard Ford lease?
Standard lease agreements cover major mechanical defects under the factory 3-year/36,000-mile bumper-to-bumper warranty, but routine scheduled maintenance such as fluid changes, tire rotations, and cabin air filter replacements remain the driver's responsibility unless an optional maintenance package is included at signing.
Q: What wear and tear charges should I expect when returning a leased vehicle?
Leasing companies allow normal wear and tear, including minor paint scratches under two inches, light tire tread wear, and small interior scuffs. Excess wear-and-tear charges apply to un-repaired body denting, cracked windshield glass, worn tires below minimum safety tread depths, or deep interior upholstery stains.
Q: Can I purchase my leased Ford model before the lease term expires?
Yes, drivers can execute an early lease buyout at any point during the agreement term. The purchase price equals the remaining capitalized cost balance plus the predetermined residual value and any applicable purchase option fees outlined in the original contract.
Engine & Performance
Powertrain specs by trim
| Feature | Active AWD | Active FWD | Platinum AWD | ST-Line AWD |
|---|---|---|---|---|
| Engine | 1.5L | 1.5L | 2L | 1.5L |
| Horsepower | 180 hp | 180 hp | 250 hp | 180 hp |
| Torque | 199 lb-ft | 199 lb-ft | 280 lb-ft | 199 lb-ft |
| Transmission | automatic 8-speed | automatic 8-speed | SelectShift® | automatic 8-speed |
| Drivetrain | All-wheel drive | Front-wheel drive | All-wheel drive | All-wheel drive |
Engine & Performance (continued)
| Feature | ST-Line Elite AWD 2.0L | ST-Line FWD | ST-Line Select AWD 2.0L |
|---|---|---|---|
| Engine | 2L | 1.5L | 2L |
| Horsepower | 250 hp | 180 hp | 250 hp |
| Torque | 280 lb-ft | 199 lb-ft | 280 lb-ft |
| Transmission | SelectShift® | automatic 8-speed | SelectShift® |
| Drivetrain | All-wheel drive | Front-wheel drive | All-wheel drive |
Exploring Your Ford Leasing Options at Tri State Ford
Navigating lease choices requires evaluating your daily driving patterns, monthly budget goals, and preference for new automotive technology to select the ideal Ford model and contract terms.
At Tri State Ford, our team helps drivers evaluate lease options, review current manufacturer incentives, and structure agreements tailored to their driving needs. Whether you want a compact Ford Escape for daily commuting or a midsize SUV like the Ford Edge, leasing offers an accessible path to driving a new vehicle backed by factory warranty protection.
To start your lease search, view our current online inventory, review trade-in estimates, or visit our showroom floor. Take the next step today by visiting our sales floor or calling our friendly team at (330) 462-7578 to schedule a test drive and explore personalized lease options.
Keep Your Vehicle Running Strong
Keep your vehicle performing at its best with our service team: