Trading in a vehicle that still has an active auto loan is a straightforward process where the dealership pays off your remaining loan balance and applies any remaining equity toward your new purchase. The dealership contacts your lender directly to obtain an official payoff statement, calculates the difference between your car's fair market trade-in value and what you owe, and handles the electronic transfer of funds to close out your original lien. If your vehicle is worth more than the loan balance, the positive equity acts as a cash down payment. If you owe more than the current value, the negative equity must be paid up front or rolled into the financing of your next vehicle.
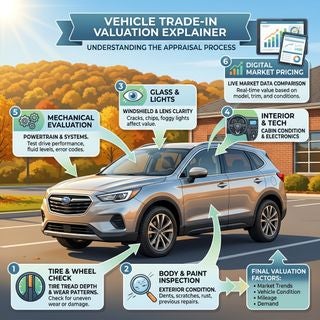
When you arrive at the showroom, our team performs a complete physical inspection and vehicle valuation to determine current market worth. Once a trade-in value is established, we contact your lienholder to verify the exact payoff figure. For drivers navigating the steep riverfront bluffs along East Liverpool, having a vehicle with reliable all-wheel drive or advanced driver-assist features like Pre-Collision Assist with Automatic Emergency Braking is essential for peace of mind during winter commutes. Upgrading to a newer truck or SUV before your current loan is fully paid off allows you to transition into enhanced safety and towing capabilities without waiting years for loan completion.
The entire transaction is consolidated into a single agreement. The dealership assumes responsibility for remitting the exact payoff amount to your bank or finance company, releasing you from your old account once the lender processes the final payment. To start the process or ask questions about your current loan status, visit our showroom on Pennsylvania Avenue or give our staff a quick call today.
Table of Contents
- How Do You Calculate Your Vehicle Equity and Handle Negative Equity?
- What Are the Financial Risks of Rolling Over Negative Equity into a New Loan?
- Why Do Dealerships Require a 10-Day Payoff Quote and Specific Title Paperwork?
- How Does Trading In at a Dealership Compare to Selling a Financed Car Privately?
- Common Questions About Trading In a Financed Vehicle
- Ready to Upgrade? How a Local Dealership Simplifies Your Financed Trade-In
How Do You Calculate Your Vehicle Equity and Handle Negative Equity?
Calculating your vehicle equity requires subtracting your official loan payoff amount from your vehicle's current market trade-in value. A positive result means you have positive equity, which reduces the total purchase price of your next vehicle. A negative result means you have negative equity—frequently referred to as being underwater or upside down—meaning your loan balance exceeds what the car is currently worth on the trade market.
To determine where you stand financially, follow these three steps:
- Obtain a formal payoff quote from your current auto lender, which includes total principal and daily accrued interest.
- Request an objective trade-in evaluation based on your vehicle's condition, mileage, and trim options.
- Subtract the payoff amount from the appraised trade value to identify your net equity position.
For example, if your current vehicle is valued at $18,000 and your official lender payoff is $14,000, you hold $4,000 in positive equity. That $4,000 functions directly as a cash credit, lowering the total amount financed on a new SUV with plenty of cargo space and space for the whole family. Conversely, if your car appraises at $12,000 but your payoff statement reads $15,000, you face $3,000 in negative equity.
When dealing with negative equity, buyers have several practical options:
- Pay the difference out of pocket at closing using cash to keep your replacement loan clean.
- Apply a cash down payment to offset the negative balance partially or entirely.
- Roll the remaining balance into your new vehicle's financing agreement if lender loan-to-value limits allow.
- Delay your trade-in while making additional principal-only payments to bridge the financial gap.
Suburban commuters traveling Route 170 through Calcutta often choose to trade in earlier when upgrading to models equipped with intelligent 4WD and BLIS with Cross-Traffic Alert to handle changing road conditions safely. Exploring our new vehicle inventory gives you a clear look at current models featuring SYNC 4 technology, while browsing our pre-owned 1-owner vehicles offers affordable pathways to secure built tough durability and Ford's proven quality.
What Are the Financial Risks of Rolling Over Negative Equity into a New Loan?
Rolling negative equity into a new car loan increases the total principal amount you finance, elevates your monthly payment, and escalates overall interest charges across the loan term. When you transfer unpaid debt from a previous vehicle into a new contract, you begin the new loan owing significantly more than the replacement vehicle's actual market value.
Industry data from Edmunds highlights that roughly 31% of vehicle trade-ins involved negative equity, with the average debt shortfall reaching approximately $7,183. Compounding debt in this manner creates several specific financial challenges:
- Deeper Negative Equity: Carrying existing debt into a new loan puts you underwater from day one, making it harder to build positive equity as the new vehicle depreciates.
- Higher Monthly Costs: Because you are financing the replacement vehicle's purchase price plus the unpaid balance of the old loan, your monthly payment rises substantially.
- Increased Interest Overhead: You end up paying interest charges on the old vehicle's debt for the duration of your new loan term.
- Insurance Risk: If the replacement vehicle is written off in an accident or stolen, standard auto insurance only covers the fair market value of the car. Without specialized gap coverage, you remain personally responsible for paying off the remaining loan balance, including the rolled-over negative equity.
To limit these risks, applying a cash down payment at closing directly reduces financed debt. Buyers can also select shorter loan terms to pay down principal faster, ensuring equity builds at a pace that keeps up with normal vehicle depreciation. Choosing a well-equipped truck with a high towing capacity and reliable EcoBoost engine performance helps retain strong market value over time. Completing an online credit application helps clarify your financing structure, while reviewing our Ford certified pre-owned inventory provides options backed by a 12-month/12,000-mile comprehensive limited warranty and a 7-year/100,000-mile powertrain limited warranty.
Why Do Dealerships Require a 10-Day Payoff Quote and Specific Title Paperwork?
Dealerships require a 10-day payoff quote because auto loan interest accrues on a daily per-diem basis, making your standard monthly statement figure inaccurate for loan satisfaction. A 10-day payoff statement calculates the exact principal balance plus ten additional days of projected interest, ensuring that funds mailed or electronically transferred to your lender cover the debt in full without leaving a residual balance.
When trading in a vehicle with an active lien, bringing the proper documentation speeds up transaction processing and prevents funding delays. While you do not need the physical paper title—since your bank or credit union holds the legal title until the lien is satisfied—you must present specific ownership verification documents at the dealership:
- 10-Day Payoff Quote: A official document generated by your lender listing the total payoff figure, daily interest rate, payoff expiration date, and remittance address.
- Account Information: Your current auto loan account number and customer service contact details for the financial institution holding the lien.
- Valid Driver's License: Government-issued identification for all individuals listed on the current loan and vehicle registration.
- Current Vehicle Registration: Active registration documents matching the names on the financing contract.
- Proof of Income and Residency: Pay stubs and recent utility bills if you plan to finance your replacement vehicle on the same day.
- All Vehicle Keys and Accessories: Factory key fobs, owner's manuals, and original equipment like cargo covers or floor mats to ensure full trade-in value.
Our finance team handles direct communication with your bank, verifying payoff details and submitting final settlement funds once agreements are signed. Business owners managing commercial fleets or hauling equipment can streamline vehicle upgrades by browsing our F-Series work truck inventory to find commercial-grade trucks engineered with maximum payload capacity and integrated trailer brake controllers.
How Does Trading In at a Dealership Compare to Selling a Financed Car Privately?
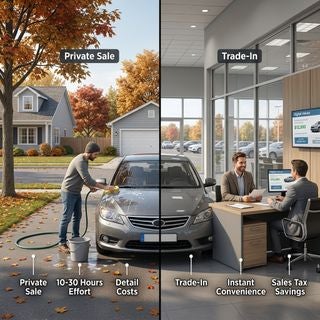
Trading in a financed vehicle at a dealership eliminates administrative hassle by allowing the dealer to satisfy the lien and transfer ownership directly, whereas selling privately requires arranging complex bank transfers before the lender releases the title to a private buyer. Private sales often yield a slightly higher gross selling price, but navigating a private sale with an active bank lien involves significant logistical hurdles.
| Process Step | Dealership Trade-In | Private Party Sale |
|---|---|---|
| Lender Payoff | Handled directly by dealer finance staff [1] | Seller must coordinate buyer funds to satisfy bank lien [8] |
| Title Transfer | Electronic lien release managed seamlessly by dealership [1] | Delays occur while waiting for bank to mail paper title [8] |
| Transaction Speed | Completed same-day in a single appointment [1] | Can take weeks to arrange buyer financing and title release [8] |
| Sales Tax Impact | Trade-in value reduces taxable amount on new vehicle in many states [1, 2] | Full sales tax paid on replacement vehicle purchase price [1] |
| Safety & Convenience | Secure, professional environment with immediate trade processing [1] | Requires meetings with strangers and personal payment risks [8] |
In a private transaction, prospective buyers are often hesitant to hand over cash or personal checks while a bank holds the physical title. The buyer must either send payment directly to your lender or meet you at a local bank branch to finalize loan satisfaction, after which the bank mails the clear title weeks later.
Conversely, trading in your car at a professional dealership offers immediate convenience and potential tax savings. In many jurisdictions, the value of your trade-in is subtracted from the sale price of the new vehicle before sales tax is calculated, saving you hundreds of dollars that private sales do not offset. Visiting our local Ford dealer location allows you to complete the trade appraisal, lien payoff, and new vehicle selection during one seamless visit.
Common Questions About Trading In a Financed Vehicle
Q: Does trading in a financed car impact your credit score?
Trading in a financed car can cause a brief, minor shift in your credit score, but settling the loan balance is beneficial over time. When the dealership remits payment to your lender, your original loan account is closed and reported as paid in full. If you finance a replacement vehicle, a hard credit inquiry occurs during application processing, and a new account opens. Making prompt monthly payments on the replacement loan establishes positive credit history and rebuilds your score quickly.
Q: Do you need to contact your lender before bringing your vehicle to the dealership?
While our dealership finance department can contact your lender on your behalf, reaching out to your lender prior to your visit is helpful. Requesting a 10-day payoff quote directly gives you clear sight of your exact loan balance before appraisals begin. Knowing your payoff amount in advance allows you to calculate your equity position accurately, evaluate your budget, and streamline your trade-in transaction once you arrive at the showroom.
Q: Can you trade in a vehicle if you owe more than its market value?
Yes, you can trade in a vehicle even if you owe more than its fair market value. The difference between your payoff figure and trade valuation represents negative equity. You can satisfy this balance by paying cash at closing, applying a down payment, or rolling the remaining debt into your new vehicle loan if lender guidelines permit. Paying cash or supplying a down payment is recommended to avoid inflating the principal balance on your replacement vehicle.
Q: What happens to your existing car loan once the trade-in agreement is signed?
Once trade-in documents are signed, the dealership submits payment directly to your lienholder to cover the agreed 10-day payoff amount. It typically takes between five and fourteen business days for financial institutions to process incoming funds and mark accounts as paid in full. You should monitor your online loan portal or contact your lender to confirm receipt of funds. If a scheduled automatic payment falls within that processing window, confirm with your bank whether to pause it temporarily.
Q: How does a down payment affect a trade-in with negative equity?
A cash down payment helps absorb negative equity during a trade-in transaction. Instead of adding the debt shortfall directly to your replacement loan, your cash down payment absorbs the negative balance first. For instance, if you have $2,000 in negative equity and provide a $3,000 cash down payment, $2,000 eliminates the old debt and $1,000 directly reduces the purchase price of your replacement vehicle. Exploring current manufacturer specials can also offer factory incentives that further offset trade-in shortfalls.
Ready to Upgrade? How a Local Dealership Simplifies Your Financed Trade-In
In our local dealership, over 70% of customers trade in financed vehicles smoothly with expert support throughout the process. We manage all lender communications, secure accurate 10-day payoff figures, and handle title transfers so you can transition into your next vehicle without stress. Whether you need an efficient commuter car with smartphone integration like Apple CarPlay and Android Auto, or a spacious family vehicle equipped with Co-Pilot360, we provide clear guidance at every step.
Our staff evaluates your trade-in using up-to-date market data to ensure you receive a fair, competitive value. Before stopping in, you can start the appraisal process online to get a clear picture of your current vehicle equity. Stop by our East Liverpool showroom, give our team a call, or use our convenient trade-in valuation tool to begin your vehicle upgrade today.
Keep Your Vehicle Running Strong
Keep your vehicle performing at its best with our service team: